The Importance of Specialist Legal Insight When Investigating Stillbirth Causes

The Importance of Specialist Legal Insight When Investigating Stillbirth Causes

The majority of families whose lives are torn apart by stillbirth are given a report by the hospital. It details what occurred; explains that various measures broke down, and frequently makes some well-meaning suggestions. What that document almost never contains is the unembellished response to the question any parent truly wants to be addressed: was it errors that led to the loss of our child?

That discrepancy among official process and clinical reality is where specialist legal guidance is required. Not in a litigious sense, but as a type of medical instrument, a method of acquiring the practical, accurate details that in-house inquiries are not constructed to examine.

Why Internal Investigations Fall Short

Hospitals have their own processes for reviewing maternity incidents. Some of these reviews are detailed. Many are not, and even the most detailed are undermined by the same institutional pressures, resources, and time constraints that meant those plans and protocols existed only on paper.

The HSIB was established because, as its first investigations have repeatedly shown, internal maternity reviews often fail to identify the same failures mentioned in this paragraph; pre-existing systemic failings that made each of these cases more likely to happen. The same missed warning signs and near-identikit paths to avoidable tragedy stretching back weeks, months, or years; the same witnesses across different staff members, different shifts, and different decisions.

Hospital reviews might note the absence of a cardiotocograph. An inquest, in one of the most common comments from coroners, will ask why, even when the CTG was in use, its ominous details might have been misunderstood or overlooked.

Even if negligence is evident, a claim will only be successful if causation can be established. The legal issue is not "did the hospital make a mistake?" but "had the error not been made, would the baby be alive?"

It’s a much tougher hurdle to overcome than people realize. Take placental abruption for example. It’s a rare but leading cause of stillbirth worldwide and causes a foetus to be deprived of oxygen and nutrients. Even in the complete absence of any clinical negligence and with optimal treatment, it is still one of the most common and devastating causes of late stillbirth.

To prove that poor medical treatment made a difference to the outcome and that earlier delivery would have led to life dependency or autism or cerebral palsy or other brain injuries requires detailed analysis and written evidence from some of the country’s foremost experts on midwifery and obstetrics. Those witnesses would not have any involvement in the care of the family and may not even work in the same country that the hospital is located in. Their role is to forensically examine the deceased child’s and mother’s medical records and care, line by line, and impartially point out any departures from good medical practice.

This level of investigation and expert reporting is usually only available through a formal Stillbirth Claim as NHS Trusts won’t voluntarily pay the cost of funding independent medical evidence.

The Red Flags A Specialist Knows To Look For

The key to proving the avoidability of a stillbirth is the deceptively simple question: What would a competent doctor or midwife have done when faced with the same symptoms, test results, and monitoring findings, in the same circumstances?

The only way to answer that question is to know contemporary professional guidelines, local policies, and research; to understand how pregnancy and its complications can interplay with each other; and to have an instinctive grasp of what a specific baby’s patterns of movement, growth and heartbeat may indicate.

Faced with an avoidable death, a skilled solicitor will mine your notes for lost opportunities. They know that seeking records from the hospital is like playing hide and seek; sometimes there are gaps that ought to be there and aren’t for very good reasons. They know what to look for, and where.

Beyond Compensation

Many families who take out a stillbirth death claim are not motivated by money. The statutory damages available for bereavement are paltry, and no sum can make good that loss. What they want, what propels them through a process that obliges them to re-experience the worst day of their lives, is for someone to say sorry, and to promise to change.

The psychological injury is also real and significant. PTSD following stillbirth is well-established and part of the legal claim. However, parents will often tell you that the legal process itself was important for them, because it was the first time anyone was compelled to be straight with them.

There is a kind of litigation that is entirely financial. This is not it. A stillbirth claim, when informed by specialist legal expertise, operates as an independent form of scrutiny which a hospital’s internal review process cannot replicate. For families who suspect that their baby’s death was avoidable, that scrutiny is not antagonistic. It’s the closest thing to the truth that they’re going to get.

How to Talk About Money and Budgeting with Your Children: Essential Tips for Financial Literacy

Talking about money can be challenging, especially when it comes to children. Establishing a foundation for financial literacy early on can lead to more responsible spending habits in adulthood. Teach children the basics of budgeting by using real-life examples and encouraging them to set savings goals.

Engaging them in conversations about family finances serves not only to demystify money but also empowers them to make informed choices. It’s essential to create a comfortable environment where they feel safe to ask questions and express their thoughts. By introducing concepts like saving, spending wisely, and the value of money, parents can equip their children with the tools they need for financial success.

Learning to talk about money opens up essential life lessons. Children who understand budgeting can develop strong financial skills that will benefit them throughout their lives. An open dialogue about money fosters a sense of responsibility and prepares them for the financial decisions they will face in the future.

Why Financial Conversations With Children Matter

Engaging children in discussions about money sets the foundation for their financial well-being. These conversations promote financial literacy and foster healthy mindsets towards money management.

Building Financial Literacy

Financial literacy is essential for navigating today’s economy. By discussing money matters with children, parents can introduce fundamental concepts such as saving, spending, and budgeting.

Key Topics to Cover:

  • Saving: Teach the importance of saving for future needs and goals.
  • Budgeting: Show how to allocate money wisely between different expenses.
  • Needs vs. Wants: Help children distinguish between what is necessary and what is desirable.

These lessons can empower children to make informed financial choices. Skills learned early can prevent poor financial habits later in life.

Establishing Healthy Money Mindsets

A healthy relationship with money is crucial for long-term success. Financial conversations should focus on instilling positive attitudes toward earning, spending, and saving.

Strategies to Promote a Positive Mindset:

  • Open Dialogue: Encourage children to express their thoughts and ask questions about money.
  • Model Behavior: Demonstrate sound financial practices in daily life.
  • Encourage Goal Setting: Support children in setting financial goals to attain desired items or experiences.

These practices can shape children’s views on money, helping them grow into financially responsible adults.

Age-Appropriate Ways To Teach Kids About Money

Understanding money concepts starts early and evolves with age. The approach should shift from basic principles to more complex financial skills as children grow.

Starting Early with Needs vs. Wants

At a young age, children can learn the difference between needs and wants. Parents can introduce this concept by discussing daily expenses. For example, they can point out necessities like food and shelter compared to desires like toys or candy.

Engaging children in activities can solidify this understanding. Using visual aids, such as a simple chart, listing needs and wants can be effective. Role-playing scenarios can also provide practical examples. This enhances their decision-making skills regarding spending.

Introducing Budgeting and Allowances

As children reach school age, introducing budgeting becomes important. Parents can set up an allowance system. This teaches children about managing a fixed amount of money.

Encouraging children to allocate their allowance can cultivate financial responsibility. They can categorize their spending into essential and discretionary items. Providing a simple budget template will help them track their income and expenses. This hands-on experience builds confidence in managing money.

Developing Money Management Habits

In their pre-teen years, children should start developing money management habits. Setting savings goals can motivate them to save part of their allowance. Opening a savings account can also provide a tangible way to track progress. These early lessons can also introduce the basic ideas behind wealth management, helping children understand how thoughtful financial choices build stability over time.

Discussing the importance of saving for larger purchases is vital. Teaching them about interest can help them understand the benefits of saving over time. Regular family discussions about money can reinforce these concepts, fostering a comfortable environment for financial discussions.

As children grow older, these conversations often expand to include more complex topics like long-term investment and wealth preservation. Parents who want to secure their family’s financial future may need to look beyond basic savings accounts. Working with professionals who understand local market dynamics and long-term planning can make a significant difference. For families in Illinois, finding the right wealth strategies peoria has to offer can help establish a clear path forward. This type of planning helps protect assets and prepares the next generation to manage their inheritance wisely.

Helping Children Understand Saving and Investing

Teaching children about saving and investing lays a foundation for financial literacy. It is essential to communicate the importance of both saving for future needs and understanding how to grow money through investments.

Explaining Savings Accounts

A savings account is an excellent starting point for children. It serves as a safe place where they can store money while earning interest.

Children can learn how to open a savings account at a local bank or credit union, often with a small initial deposit. Key concepts include:

  • Interest: Explain how money increases over time.
  • Deposits and Withdrawals: Teach them how to add and take out money responsibly.
  • Goals: Help them set savings goals, such as a toy or game.

Using a chart can visually show how savings grow over time with interest. This can make the concept more relatable and tangible.

Introducing Investment Concepts

Investing involves using money to generate a return over time. Kids can grasp this by introducing simple investment concepts.

Start with basic ideas like:

  • Stocks and Bonds: Explain how buying shares means owning a part of a company.
  • Risk vs. Reward: Discuss how investments can grow but also carry risks. Visual aids like graphs showing potential growth can be helpful.

Consider using simulations or child-friendly investment apps to make learning engaging. Children can see how their chosen investments perform, fostering an interactive experience. This can help them understand the importance of patience and strategy in investing.

Guiding Kids Toward Good Financial Decisions

Teaching children about money management is essential for their future independence and financial security. Parents play a crucial role in guiding them through various aspects of budgeting and responsible financial practices.

Discussing Credit Cards Responsibly

It is important to introduce children to the concept of credit cards early on. Parents can explain how credit cards work, emphasizing the need for responsible usage.

  • Set Limits: Discussing spending limits can help children understand the importance of staying within their means.
  • Monthly Bills: Show them how credit card bills arrive and the importance of paying them on time.
  • Interest Rates: Clarifying that unpaid balances incur interest can illustrate the costs associated with borrowing money.

Encouraging responsible use through monitored practice will help children develop good habits.

Teaching The Importance Of A Good Credit Score

A good credit score significantly affects financial opportunities. Parents should explain its relevance and how credit scores are formulated.

  • Payment History: Emphasize the importance of making payments on time.
  • Credit Utilization: Teach children to maintain low balances relative to their credit limits.
  • Impact of Inquiries: Explain how applying for new credit affects scores and should be done judiciously.

Using real-life examples, such as applying for a loan or renting an apartment, can highlight the practical implications of a good credit score.

When To Consult A Financial Advisor

Financial advisors can provide specialized guidance tailored to individual goals. Parents should explain when seeking such assistance is beneficial.

  • Life Transitions: Discuss important milestones, like college or starting a family, when professional advice may be needed.
  • Investment Education: Explaining investment options can motivate discussions around the benefits of speaking with experts.
  • Proactive Planning: Parents can share examples of how planning for retirement or major purchases can be improved with professional help.

This guidance often extends beyond simple investment tips, encompassing a holistic view of one’s financial life. For families, this might involve crafting strategies for college savings, retirement planning, and even estate considerations. A comprehensive approach ensures that all aspects of financial well-being are addressed, adapting to life’s changes and market shifts. Seeking out a firm like Florida Wealth Advisory can provide the expertise needed to navigate these complex areas, offering tailored solutions for long-term financial security.

Passing Down Family Wealth Wisdom

Families can share their own financial experiences and lessons learned over generations. This practice helps children gain valuable insights.

  • Open Conversations: Parents should foster open discussions about financial successes and mistakes.
  • Family Values: Sharing values relating to money management, such as saving versus spending, can shape children’s attitudes.
  • Legacy Planning: Discussing how family wealth is distributed can establish an understanding of financial responsibility and legacy.

Teaching children the significance of wealth management helps them prepare for their financial futures.

Cost-Effective Ways to Set Up a Nursery: Smart Strategies for Budget-Friendly Planning

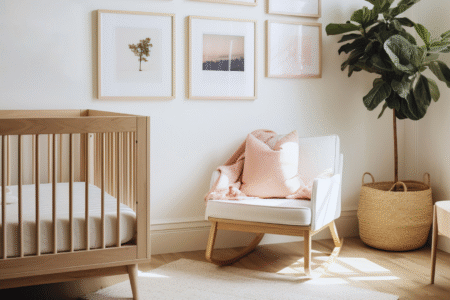
Setting up a nursery can often feel overwhelming, especially when considering the associated costs. Many parents want to create a beautiful and functional space for their newborns without breaking the bank. Cost-effective ways to set up a nursery include prioritizing essential items, repurposing furniture, and shopping secondhand for decor.

Thinking creatively can lead to significant savings. For instance, choosing a multifunctional crib that converts into a toddler bed eliminates the need for separate purchases later. Additionally, DIY projects can add a personal touch while keeping expenditures low.

Budget-friendly solutions do not mean sacrificing style or quality. With careful planning and smart shopping, it is possible to design a nursery that is both affordable and aesthetically pleasing, making it a welcoming environment for the new addition to the family.

Planning a Cost-Effective Nursery Layout

Creating an efficient nursery layout requires careful planning. By setting a budget, choosing a gender-neutral design, and maximizing available space, parents can achieve an inviting and functional environment for their baby.

Setting a Realistic Nursery Budget

Establishing a clear budget is vital. Parents should start by listing essential items, such as a crib, changing table, and storage solutions.

  • Prioritize Needs: Focus on necessities first.
  • Estimate Costs: Use local retail prices to estimate total expenses.
  • Unexpected Expenses: Allocate a small portion for unforeseen costs, like decor or accessories.

Researching sales and utilizing discount retailers can significantly reduce expenses. It’s also beneficial to consider second-hand options, which can offer quality items at a fraction of the price.

Choosing a Gender-Neutral Nursery Design

A gender-neutral nursery design provides versatility. Parents can select colors and themes that suit any baby, creating a calm and welcoming space.

  • Color Palette: Choose soft yellows, greens, or grays instead of traditional pinks or blues.
  • Decals and Artwork: Incorporate gender-neutral themes, such as animals or nature.
  • Furniture Selection: Opt for versatile furniture that can be used as the child grows, like a convertible crib.

This approach not only saves money but also allows future updates without a complete redesign.

Finding the Best Lighting

There’s no need to splurge on expensive lighting fixtures when setting up a nursery. Simple, thoughtful choices can create a warm and cozy space without overspending.

  • Maximize Daylight: Placing the crib and play area near windows allows natural sunlight to gently brighten the room, creating a cheerful and soothing atmosphere for the baby. Sunlight can also help regulate the baby’s sleep-wake cycle naturally. Just be sure to use light-filtering curtains to soften direct rays and maintain comfort throughout the day.
  • Window Treatments: Choosing the right window treatments, like light-filtering curtains or simple Custom Blinds can manage sunlight while keeping the nursery warm and inviting. For nap times, blackout shades or soft shutters work well to block out excess light and create a peaceful sleep environment. This balance between brightness and comfort makes the room more functional throughout the day.
  • Soft Night Lighting: Opting for dimmable LED night lights is a smart way to create a gentle, soothing glow during nighttime feedings or diaper changes. These lights offer enough visibility for parents without disrupting the baby’s sleep. The adjustable brightness helps maintain a calm environment and prevents overstimulation.

With thoughtful lighting choices and smart use of natural light, a nursery can be both practical and peaceful, providing a nurturing space for the baby and a comforting environment for parents.

Beyond fixtures and curtains, consider how tailored window coverings can improve nap quality and room comfort. Made-to-measure options minimise gaps and light seepage while offering better insulation, which helps keep temperatures steady for sleeping babies.

For parents who prioritise safety and precise fitting, Bespoke window shutters can provide a cordless, easy-to-clean solution that also enhances privacy and light control. Choosing the right covering can make daytime naps more reliable without sacrificing the nursery’s style.

Maximizing Small Nursery Spaces

For parents with limited room, efficient use of space is essential.

  • Multi-Functional Furniture: Select a crib with built-in storage or a changing table that doubles as a dresser.
  • Vertical Space: Utilize wall shelves for books and toys, keeping floors clear.
  • Organizational Solutions: Invest in bins and baskets for easy access to baby essentials without clutter.

With thoughtful planning, even the smallest nursery can be functional and stylish.

Prioritizing Nursery Safety

Creating a safe nursery environment is one of the most important aspects of preparing for a new baby.

  • Electrical Safety: Outlet covers should be placed on all unused sockets to prevent accidental contact. Cords from blinds, lamps, or monitors must be secured and kept out of reach. Cordless window coverings are a safer alternative to reduce strangulation hazards.
  • Safe Flooring: Waterproof vinyl flooring offers a practical choice when it comes to reducing the risk of slips and falls, especially in spaces designed for babies. For a proper fit and finish, reaching out to professionals who specialise in waterproof vinyl flooring Buford, GA, or elsewhere, can help ensure quality installation. Also, adding non-slip rugs or carpets on top can provide an extra layer of comfort and protection as little ones begin to explore on hands and knees.
  • Non-Toxic Materials: Low-VOC paints, untreated wood furniture, and organic fabrics are healthier choices for a nursery environment. These materials help reduce exposure to chemicals and fumes that may affect a baby’s sensitive system. Prioritizing safer options supports better indoor air quality and overall well-being.

Careful attention to these safety considerations ensures the nursery is not only beautiful and functional, but also secure and supportive for the baby’s first months and years.

Beyond these visible safety measures, it’s equally important to pay attention to the home’s air system. Regular inspections and servicing of the heating, ventilation, and air conditioning system help maintain clean, healthy air in the nursery. A well-kept system prevents dust buildup, mold growth, and poor humidity control, all of which can affect a baby’s breathing and comfort.

Routine tune-ups also improve energy efficiency, meaning the system doesn’t have to work as hard to regulate temperature, saving on utility bills and reducing the risk of costly repairs down the road. This makes HVAC maintenance not only a safeguard for health but also a smart, cost-effective choice for long-term home care. For reliable service, companies like Platinum Air Heating & Cooling can provide the expertise needed to keep everything running smoothly.

Affordable Nursery Furniture Essentials

Creating a functional and stylish nursery doesn’t have to come with a hefty price tag. Focused shopping and smart choices can lead to significant savings on essential nursery furniture.

Where to Find Budget-Friendly Cribs

When searching for affordable cribs, consider looking at second-hand options. Websites and apps like Facebook Marketplace, Craigslist, and OfferUp often feature gently-used cribs at a fraction of the original price.

Retailers known for budget-friendly cribs include:

  • IKEA: Offers modern designs with safety features at lower prices.
  • Target: Frequently has sales and promotions on baby furniture.
  • Walmart: Stocks a variety of affordable options with good reviews.

Make sure any crib meets current safety standards. Check for recalls and inspect the condition to ensure it’s safe for the baby.

Selecting a Cost-Effective Changing Table

A changing table is essential for any nursery, but it doesn’t need to be pricey. Many parents opt for dressers with a changing pad on top. This dual-purpose approach saves money and space.

Consider these options for budget-friendly changing tables:

  • IKEA: Known for economical designs that maximize the use of space.
  • Online marketplaces: Like Amazon and Wayfair, often have sales on changing tables.
  • DIY solutions: Repurposing a sturdy dresser can be both cost-effective and stylish.

Ensure the changing table has safety straps and storage options for baby gear and diapers, which adds convenience while saving money.

Choosing a Multipurpose Rocking Chair

A rocking chair or glider provides comfort during feeding and soothing sessions. Opting for a multipurpose chair can maximize space and budget.

Look for features like:

  • Sturdy construction: Ensures safety and longevity.
  • Removable cushions: Easier cleaning for spills and messes.
  • Compact design: Ideal for smaller nurseries while still providing comfort.

Retailers such as Target, IKEA, and even thrift shops can offer affordable options. A gentle rocking chair can also serve as a cozy reading spot as the child grows.

Saving on Nursery Accessories and Decor

Creating an appealing nursery does not have to strain the budget. There are numerous affordable ways to add personality and functionality to the space through decor and accessories.

Inexpensive Gallery Wall Ideas

A gallery wall can add character without high costs. Parents can curate a mix of personal photos and artwork.

  • DIY Artwork: Use prints from online resources or let children create their own pieces.
  • Frame Options: Thrift stores often have inexpensive frames. These can be painted or left as is for a quirky touch.
  • Varied Sizes: Mixing frame sizes and styles creates interest without requiring uniformity.

This approach allows for personal expression and can be changed as the child grows.

Affordable Stuffed Animals and Toys

Stuffed animals are a staple in any nursery, but they don’t need to be costly. Finding affordable options can contribute to a cheerful environment.

  • Second-Hand Finds: Stores and online marketplaces often have gently used stuffed animals at a fraction of the retail price.
  • Sales and Discounts: Keeping an eye on holiday sales can lead to significant savings.
  • DIY Stuffed Toys: For those who are crafty, making stuffed animals from fabric scraps is a meaningful and budget-conscious option.

Opting for a few well-placed toys can also reduce clutter, making the nursery feel more organized.

Cost-Effective Decorative Storage Solutions

Storage is vital in a nursery, and there are many creative ways to make it both practical and stylish.

  • Baskets: Using wicker or fabric baskets can keep toys organized. These can often be found at low prices at discount stores.
  • Shelves: Wall-mounted shelves are functional and reduce floor clutter. They can hold decorative items and books within easy reach.
  • Multi-functional Furniture: Furniture with built-in storage, such as benches or ottomans, provides extra space while serving a dual purpose.

Using smart storage solutions can make a space feel larger and more functional without a hefty investment.

Smart Strategies for Everyday Nursery Savings

Effective nursery savings can be achieved through careful planning and resourcefulness. By focusing on bulk purchases, secondhand options, and DIY projects, parents can significantly reduce expenses while ensuring their baby’s needs are met.

Buying Diapers in Bulk

Diapers are a major expense in any nursery. Purchasing them in bulk offers substantial savings.

  • Store Promotions: Many retailers provide discounts when buying larger quantities. Look for sales events and clearance items.
  • Subscriptions: Some companies offer diaper subscription services that deliver diapers at a discount. This often includes free shipping.
  • Generic Brands: Consider opting for store-brand diapers. They frequently have a similar quality to name brands at a reduced cost.

Budgeting for these purchases can further enhance savings, making diapering more cost-effective.

Embracing Secondhand Baby Gear

Baby gear can be incredibly pricey, but secondhand options provide an economical alternative.

  • Local Marketplaces: Websites and local groups often feature gently used baby items. This includes cribs, strollers, and toys.
  • Consignment Shops: These stores specialize in selling secondhand baby gear at lower prices. They also offer the advantage of inspecting items for quality.
  • Safety Standards: It’s essential to check that all gear meets current safety standards. This ensures that both savings and safety are prioritized.

Spending money wisely on baby gear can lead to significant savings without sacrificing quality.

DIY Nursery Projects for Cost Savings

Creating a nursery doesn’t have to mean high costs. DIY projects can add a personal touch and save money.

  • Decorative Items: Parents can make their own wall art or mobiles using inexpensive materials. This allows for creativity while keeping costs low.
  • Furniture Upcycling: Repurposing or refurbishing old furniture reduces costs significantly compared to buying new items. A coat of paint or new hardware can transform a piece.
  • Educative Projects: Crafting not only saves money but also offers an opportunity to bond with family members involved in the creation.

DIY projects enable parents to design a unique space tailored to their baby’s needs while remaining mindful of expenses.

Baby Budgeting Tips for First-Time Parents: Essential Strategies for Financial Success

Welcoming a baby brings immense joy, but it also brings significant financial changes. Establishing a budget early can help parents manage new expenses while preparing for the unexpected. Understanding where the money will go is essential for a smooth transition into parenthood.

Many first-time parents are surprised by the costs associated with a new baby. From diapers and formula to medical expenses and baby gear, these expenses can quickly add up. By planning ahead and creating a comprehensive budget, parents can reduce stress and ensure they are financially prepared for their new arrival.

Implementing effective budgeting tips can help parents prioritize spending and make informed decisions. Exploring cost-effective options and understanding necessary versus optional purchases will empower parents to navigate this new chapter confidently.

Preparing a home for a new arrival often requires making physical space in addition to financial planning. Many families find they need to clear out spare rooms or home offices to set up a nursery. Instead of selling off valuable furniture or personal belongings, renting a temporary storage unit is a practical solution. Working with a storage company locals trust keeps these items safe and out of the way until they are needed again. This approach helps parents keep their homes organized without the pressure of immediate decluttering decisions.

Setting Up a Realistic Baby Budget

Creating a realistic baby budget is essential for first-time parents as they navigate the financial aspects of welcoming a new child. Identifying costs and prioritizing expenses can help in establishing a solid financial plan.

Estimating the Cost of Raising a Child

The cost of raising a child can vary widely based on location and individual circumstances. On average, parents can expect to spend between $12,000 to $15,000 annually on their child in the first few years of life.

Key expenses include:

  • Healthcare: Routine check-ups and vaccinations.
  • Diapers and wipes: Regular replenishment is necessary.
  • Clothing: Babies grow quickly, resulting in frequent purchases.

It’s important to factor in both expected and unexpected expenses to avoid surprises.

Identifying Essential Expenses for New Parents

Essential expenses for new parents include items required for the baby’s daily care. Prioritizing these will help create a comprehensive budget.

  • Baby Gear: Cribs, car seats, and strollers are often necessary purchases.
  • Feeding: Formula or breast pump supplies can incur significant costs.
  • Healthcare: Costs associated with pediatric visits and vaccinations are unavoidable.
  • Childcare: If both parents work, consider the cost of daycare or nanny services.

Assessing these crucial categories helps in managing finances effectively.

Creating and Managing Your Budgeting Plan

A budgeting plan should be tailored to the family’s income and expenses. Here’s a structured approach parents can follow:

  • List Expenses: Break down monthly costs into essentials and non-essentials.
  • Set Limits: Allocate specific amounts for each category.
  • Track Spending: Use budgeting apps or spreadsheets to monitor expenses closely.

Regularly reviewing the budget allows adjustments based on changing needs and ensures financial stability. Establishing a cash reserve for emergencies can provide added security during this new phase.

Managing Essential Baby Expenses

First-time parents often face various essential expenses when welcoming a new baby. Understanding how to manage these costs effectively can help ease financial stress and ensure they are well-prepared for their new responsibilities.

Smart Shopping for Baby Gear and Car Seats

Choosing the right baby gear and car seat is crucial for safety and functionality. It’s wise to research and compare products before making purchases.

  • Consider buying second-hand items: Gently used gear and car seats can provide savings, but ensure they meet safety standards and have not been recalled.
  • Look for sales and discounts: Major retailers often have sales on baby products, especially during holidays or special occasions.
  • Join parenting groups: Local community groups or online forums may offer advice on where to find the best deals.

Investing in versatile products, such as convertible car seats, may save money in the long run.

Saving on Diapers and Baby Food

Diapers and baby food can be significant ongoing costs for new parents. There are several strategies to reduce these expenses.

  • Use cloth diapers: While the initial cost may be higher, cloth diapers can lead to substantial savings over time compared to disposable options.
  • Sign up for subscription services: Many companies offer diaper subscription services that provide discounts for regular deliveries.
  • Buy in bulk: Purchasing diapers and baby food in larger quantities can result in lower per-unit costs.

When introducing solid foods, making homemade baby food from fruits and vegetables can also be a cost-effective choice.

Budget-Friendly Childcare Options

Childcare can be one of the largest expenses for families. Exploring affordable options can help manage this cost-effectively.

  • Consider family or friends: If possible, having a trusted family member or friend help with childcare can reduce costs significantly.
  • Look into local co-ops: Some communities have childcare co-ops where parents share responsibilities, offering care at a lower price.
  • Research state assistance programs: Various programs are available that can aid in covering childcare expenses for low-income families.

Using flexible work hours may help parents save on childcare as well.

Breastfeeding and Introducing Solid Foods

Breastfeeding can be a cost-effective way to provide nutrition for a baby. It can eliminate the need to purchase formula, saving a considerable amount.

  • Consider lactation support: Consulting with a lactation consultant can help troubleshoot any issues and encourage successful breastfeeding.
  • Plan for solid food transition: Introducing solid foods can also be budget-friendly. Parents can purchase seasonal produce to make their own baby food or simply mash soft fruits and vegetables.

By planning meals and utilizing sales, families can ensure they provide nutritious options without overspending.

Building Financial Security for Your Family

Establishing a solid financial foundation is crucial for new parents. By focusing on emergency funds, understanding insurance needs, and maximizing parental leave benefits, they can ensure stability and peace of mind during this transformative period.

Emergency Fund Planning for New Parents

Creating an emergency fund is vital for families. New parents should aim to save three to six months’ worth of living expenses. This fund offers protection against unexpected costs, such as medical expenses or job loss.

For example, as babies transition to solid foods, their chewing and swallowing habits affect how their jaw and airway develop. Some parents notice issues like mouth breathing or snoring early on, which can impact a child’s sleep and focus. Addressing these concerns early with specialized programs like myowaycenters.com/ helps support healthy growth. Taking care of these developmental needs early can prevent more expensive speech or dental treatments later in life.

To start, they can set aside a specific amount each month into a separate account. Automating transfers can help with consistent savings. New parents might also consider using any financial gifts or bonuses to jump-start their fund.

Understanding Insurance Needs

Insurance is an essential component of financial security. New parents should evaluate their needs for various types of insurance, including life insurance and health coverage.

Life insurance provides financial support for dependents in case of unforeseen events. A term life policy, which is generally more affordable, can cover needs for a specific timeframe. Health insurance should also be reviewed to ensure adequate coverage for prenatal and postnatal care.

Maximizing Parental Leave and Benefits

Understanding parental leave policies is key for new parents. They should familiarize themselves with their workplace’s leave entitlements and government benefits, such as the Canada Child Benefit.

New parents need to know the duration and pay associated with their leave. Planning for this period can help maintain household income. They should also apply for any available benefits promptly to avoid delays in financial support.

Saving for Your Child’s Future

Planning for a child’s future involves establishing education savings and selecting the right accounts. Starting early and understanding the available options can significantly impact financial readiness for education costs.

Starting Education Savings Early

Beginning education savings as soon as possible can benefit significantly from compound interest. Parents can explore 529 plans, which allow tax-free growth for educational expenses. These plans come in two main types: College Savings Plans and Prepaid Tuition Plans.

Investing small, regular amounts can add up over time. Setting up automatic contributions can help maintain consistency. For instance, contributing $100 per month could grow to over $30,000 after 18 years, depending on investment performance.

Parents should also look into state-specific plan benefits and any available tax deductions. They may also consider other options like custodial accounts, which offer flexibility but may come with tax implications.

Choosing and Using Savings Accounts

Selecting the right savings account is critical for managing education savings. High-yield savings accounts can offer better interest rates compared to traditional savings accounts. This makes them a practical choice for short-term savings needs.

Parents can compare accounts based on interest rates, fees, and accessibility. It’s essential to check if the account allows for withdrawals without penalties, especially if funds are needed unexpectedly.

Consider setting up an emergency fund alongside the education savings for unanticipated expenses. This additional cushion can relieve some financial pressure as education costs approach. By applying a systematic approach, they can ensure adequate savings and financial security for their child’s future education needs.

Managing Money as a Couple: A Guide to Building Financial Harmony

Managing money as a couple can be challenging, but it is essential for a healthy relationship and financial stability. However, when financial matters break down—especially for unmarried couples—disputes over property or contributions may lead to legal actions such as tolata claims to determine ownership rights. Successful financial management requires open communication in couples who are focused on staying together, setting shared goals, and developing a budget that works for both partners. By approaching finances as a team, couples can alleviate stress and build a stronger foundation for their future together.

Finding the right balance in spending and saving often involves compromise and understanding each partner’s financial habits and priorities. It is important for both individuals to actively participate in discussions about financial matters, ensuring transparency and mutual respect when it comes to money decisions.

Creating a joint budget can help couples identify their financial strengths and weaknesses, fostering a sense of teamwork. By regularly revisiting their financial goals and progress, couples can stay aligned and make informed decisions that support their shared aspirations.

Understanding Joint Finances

Managing money as a couple involves understanding each partner’s financial behaviors and aligning on shared goals. Success in this area can lead to greater financial security and stronger relationships.

The Psychology of Money and Relationships

Money can influence relationships significantly. Each partner typically brings their own beliefs and habits regarding finances, shaped by upbringing and experiences. Recognizing these differences is key.

Discussions about spending and saving may trigger emotional responses. Awareness of each partner’s financial personality helps navigate conflicts. For example, one partner might prioritize saving for emergencies, while the other values enjoying the present through experiences.

Key Steps:

  • Open Communication: Share financial histories and perspectives.
  • Empathy: Acknowledge each other’s feelings related to money decisions.
  • Respect Differences: Understand that differing views can complement each other.

The Benefits of Managing Money Together

Managing finances jointly can strengthen a couple’s bond. It fosters teamwork and shared responsibility, creating a clear picture of financial health.

Benefits include:

  • Unified Goals: Working together helps establish common financial objectives.
  • Improved Budgeting: Joint oversight can lead to more efficient use of resources.
  • Transparency: Sharing accounts increases accountability and trust.

Creating a joint budget allows couples to prioritize spending while saving towards shared goals, like vacations or home purchases. This proactive approach often reduces financial stress and promotes collaboration.

Potential Challenges and How to Address Them

Couples may encounter various challenges when managing finances. Conflicting spending habits or differing risk tolerances can create tension.

To address these issues:

  • Regular Check-ins: Schedule monthly meetings to discuss finances openly.
  • Conflict Resolution: Develop strategies to navigate disagreements constructively.
  • Set Boundaries: Define individual and joint spending limits to respect personal financial preferences.

Utilizing tools like budgeting apps can help keep finances organized and transparent. Emphasizing teamwork in handling finances can transform potential friction into a shared experience.

Setting Financial Goals as a Couple

Effective financial goal-setting is essential for couples seeking to achieve their desired lifestyle and build a secure future together. Establishing a shared vision helps align both partners’ aspirations and fosters teamwork in managing finances.

Short-Term and Long-Term Goal Planning

Short-term goals often focus on accomplishments within a one-year timeframe. Common examples include saving for a vacation, paying off credit card debt, or creating an emergency fund. Couples can list these goals and assign specific monetary targets and deadlines to track progress.

In contrast, long-term goals typically extend over several years or decades. These might include saving for a home, retirement, or children’s education. Couples should create a plan that defines these objectives clearly and breaks them down into actionable steps. This approach makes it easier to visualize progress and stay motivated.

Prioritizing Goals and Allocating Resources

Once goals are set, prioritization is crucial to understand what matters most. Couples should discuss their individual priorities and identify common ground. Creating a shared ranking system can simplify decision-making.

Allocating resources effectively requires budgeting and communication. Couples should determine how much money can be set aside for each goal and establish a timeline for achievement. Regular check-ins can help adjust plans as circumstances change and ensure both partners remain engaged in the process. Using tools like spreadsheets or budgeting apps can enhance transparency and accountability in this endeavor.

Creating a Joint Budget

Establishing a joint budget is essential for couples to manage shared finances effectively. This involves tracking income, adjusting budgets as circumstances change, and utilizing budgeting tools to streamline the process.

Tracking Income and Expenses

Both partners must openly record all sources of income and every expense. This transparency ensures accountability. Couples can start by creating a comprehensive list that includes salaries, bonuses, and any secondary income.

For expenses, categorize them into fixed and variable expenses. Fixed expenses might include rent or mortgage, while variable expenses cover groceries and entertainment. A simple table can help visualize this:


Income Amount
Partner 1 Salary $3,000
Partner 2 Salary $2,500
Total Income $5,500


Expense Amount
Rent/Mortgage $1,500
Groceries $600
Utilities $250
Total Expenses $2,350

This method allows couples to see where their money goes and identify areas for savings.

Adjusting Budgets Over Time

Life changes, such as job shifts or adding family members, can impact financial situations. It is important for couples to review their budget regularly—monthly or quarterly.

During these reviews, they should assess what has changed in their income and expenses. If significant expenses arise or incomes fluctuate, they can adjust categories accordingly. For instance, if they expect an increase in childcare expenses, they might reduce spending in discretionary areas like dining out.

Flexibility and communication are vital. Both partners must be open to adjusting their contributions and spending habits as needed.

Budgeting Tools and Apps

Utilizing budgeting tools can simplify the process. Many apps are designed specifically for couples, offering features like joint access and expense tracking. Popular examples include:

  • Mint: Offers budget tracking and bill reminders.
  • YNAB (You Need A Budget): Focuses on proactive budgeting and goal setting.

Many of these tools provide visual aids to see spending habits and suggest areas for improvement.

Using these resources can aid couples in maintaining clarity about their finances and ensuring they stay on track with their financial goals.

Managing Debt and Credit

Managing debt and credit as a couple requires a cohesive approach. Effective communication and joint strategies can help reduce financial stress and build a solid foundation for future goals.

Strategies for Paying Off Debt

Couples should start by listing all debts, including amounts, interest rates, and due dates. This can create a transparent view of their combined financial responsibilities. Prioritizing debts can make repayment manageable.

Common strategies include:

  • Debt Snowball Method: Focus on paying off the smallest debt first while making minimum payments on others. This can build momentum.
  • Debt Avalanche Method: Target debts with the highest interest rates first. This often saves the most money on interest over time.

Establishing a joint budget can ensure both partners contribute to repayment efforts while avoiding additional debt.

Understanding Joint Credit

Joint credit can affect both individuals’ credit scores and financial obligations. When couples apply for credit together, they both share responsibility for the payments. This can be advantageous or disadvantageous, depending on individual financial situations.

Key points to consider:

  • Impact on Credit Scores: Missed payments will impact both credit scores. Maintaining timely payments is crucial.
  • Shared Liability: Each partner is responsible for the total debt, regardless of who incurred it. Clear communication about spending habits is vital.

Before applying for joint credit, couples should discuss their financial goals and ensure they are on the same page regarding spending and repayment practices.

Investing and Retirement Planning

Effective investment and retirement planning is essential for couples to secure their financial future. By aligning strategies and maximizing contributions, they can work towards shared goals.

Aligning Investment Strategies

Couples should begin by discussing their financial goals and risk tolerance. Identifying individual and joint objectives can help create a cohesive investment plan.

Consider these steps:

  • Set common goals: Decide on short- and long-term objectives.
  • Evaluate risk tolerance: Discuss how much risk each person is comfortable taking.
  • Select appropriate assets: Diversify investments across stocks, bonds, and other assets to balance risk and return.

Regularly review the investment strategy to adjust for changes in life circumstances or market conditions. Open communication is key to ensuring both partners feel included in financial decisions.

Retirement Accounts and Contributions

Retirement accounts, such as 401(k)s and IRAs, are crucial for building a nest egg. Couples should assess their options to maximize contributions effectively.

Important considerations include:

  • Employer-sponsored plans: Take advantage of any employer match to enhance contributions.
  • IRA options: Explore both traditional and Roth IRAs for tax benefits that suit their financial situation.
  • Monitor contributions: Adjust contributions based on financial changes, future goals, and tax implications.

Regular contributions and strategic planning can significantly impact retirement readiness. Working as a team enables couples to make informed decisions that align with their shared goals.

Beyond just saving for the future, couples should also consider the legal frameworks that protect their assets and ensure their wishes are honored. Establishing a comprehensive estate plan is a vital step in this process, as it provides clarity on how property and investments will be handled in the event of an emergency. For those living in Alberta, consulting with professionals who specialize in Red Deer wills and estates can help navigate the complexities of local inheritance laws. This proactive approach ensures that both partners are protected and that their long-term financial legacy is secure. By addressing these legal details early, couples can avoid potential disputes and provide peace of mind for their loved ones.

Emergency Funds and Insurance

Establishing a robust financial plan as a couple includes preparing for unexpected expenses. Emergencies such as medical bills, car repairs, or even a burst pipe that requires attention from plumber services Muncie IN can happen at any point and without warning. As such, emergency funds and appropriate insurance coverage are essential components that provide security and peace of mind.

Building an Emergency Savings Fund

An emergency savings fund acts as a financial safety net. Experts recommend saving three to six months’ worth of living expenses. Couples should assess their monthly expenses to determine an appropriate target.

To build this fund, they can start by setting aside a fixed amount each month. A high-yield savings account is advisable for better interest rates while keeping funds accessible.

Consider automating transfers to the savings account to promote discipline in saving. Regularly reviewing progress can help maintain motivation and ensure that the fund meets evolving needs over time.

Choosing the Right Insurance

Selecting appropriate insurance policies is crucial for couples to shield themselves from significant financial liabilities. They should evaluate options for health, auto, home, and life insurance to safeguard against unforeseen events.

When comparing policies, it’s essential to review coverage limits, deductibles, and premiums. Couples can utilize comparison tools to identify the best rates and coverage for their needs.

Consulting with an insurance agent may provide additional insights into potential discounts for bundling policies. Ensuring both partners are adequately covered while avoiding unnecessary overlaps is key to efficient financial management.

Navigating Financial Conflict

Financial disagreements are common in relationships and can create tension if not managed effectively. Establishing clear communication and considering professional guidance can help couples address and resolve conflicts.

Communication Strategies

Open and respectful dialogue is essential for navigating financial conflicts. Couples should create a safe space for discussing money matters. Setting aside time for regular conversations about finances can prevent misunderstandings.

Using “I” statements can help each partner express their feelings without assigning blame. For instance, saying “I feel anxious when expenses arise unexpectedly” can foster understanding. Active listening is crucial; partners should validate each other’s feelings and perspectives.

It might be helpful to establish a budget together and outline shared financial goals. This approach can facilitate teamwork and ensure both partners share responsibility. Regular check-ins on financial progress can further enhance collaboration.

Seeking Professional Financial Advice

When conflicts persist, seeking professional financial advice might be beneficial. A financial advisor can offer neutral perspectives and expertise to help couples make informed decisions.

Advisors can assist in developing a personalized financial plan that aligns with the couple’s goals. This can include budgeting strategies, debt management, and investment advice.

Couples should consider attending workshops or seminars focused on finance for couples. These resources can provide valuable tools for managing money together and overcoming conflicts. Having a professional mediator can sometimes clarify issues and guide discussions productively.

Regular Financial Check-Ins

Regular financial check-ins are essential for couples to maintain a healthy relationship with money. These meetings help partners stay informed about their finances, make informed decisions, and adjust their goals as needed.

Scheduling Financial Meetings

Couples should establish a regular schedule for financial meetings. Setting specific times, such as the first Sunday of every month, creates consistency. This routine allows both partners to prepare in advance and brings a sense of accountability.

During these meetings, consider discussing upcoming expenses, budgeting strategies, and any financial goals. Use a shared calendar or app to keep track of these meetings, ensuring both partners prioritize this important aspect of their relationship. Flexibility is also key; if conflicts arise, reschedule rather than skip.

Assessing Financial Health and Progress

During check-ins, partners should assess their current financial health. Start by reviewing income, expenses, and savings. A simple table can illustrate financial progress:


Category Current Amount Target Amount
Savings $5,000 $10,000
Debt $15,000 $10,000
Monthly Budget $3,000 $2,800

Focus on what has changed since the last meeting. Discuss any adjustments needed in spending habits or saving strategies.

Additionally, evaluate shared financial goals, such as saving for a home or planning a vacation. Setting measurable milestones can enhance motivation and accountability, helping couples stay aligned on their financial journey.

Estate Planning and Wills

Effective estate planning is crucial for couples to ensure their wishes are respected and their assets are managed according to their preferences. Addressing both the importance of estate planning and the necessary legal documentation can save couples from potential disputes and confusion in the future.

Importance of Estate Planning

Estate planning allows couples to specify how their assets will be distributed upon death. This process helps avoid significant stress during an emotionally challenging time.

Key benefits include:

  • Clarifying Wishes: Clearly outlined wishes prevent misunderstandings among heirs.
  • Minimizing Taxes: Strategic planning can reduce estate taxes, preserving wealth.
  • Guardianship Decisions: Couples can designate guardians for minor children, ensuring their care aligns with their values.

Without a proper estate plan, the state’s intestacy laws will determine asset distribution, which may not align with the couple’s wishes. Given the legal complications of wills, trusts, and tax law, taking assistance from a professional estate planning lawyer can ensure that all documents are legally sound and properly executed. They can also provide advice based on the specific assets and family situation.

Documentation and Legal Aspects

Proper documentation forms the backbone of estate planning. Essential documents include a will, durable power of attorney, and health care proxy. Each serves a distinct purpose:

  • Will: Distributes property and names an executor. It ensures that assets go to the designated beneficiaries.
  • Power of Attorney: Authorizes a trusted individual to make financial decisions if one partner becomes incapacitated.
  • Health Care Proxy: Designates someone to make medical decisions, reflecting the couple’s health care preferences.

These documents should be updated regularly to reflect any changes in circumstances, such as marriage, divorce, or the birth of children. Consulting an estate planning attorney ensures that all legal requirements are met and that the documents accurately reflect intentions.

Cultivating Financial Independence within the Relationship

In a partnership, it’s essential to recognize the importance of individual financial identity alongside shared financial responsibilities. Nurturing separate savings and encouraging personal growth contributes to a balanced dynamic.

Maintaining Individual Savings

Setting aside individual savings helps partners retain a sense of independence. Each person should establish a personal savings account, separate from joint finances. This allows for personal expenditures without needing mutual consent.

Steps to Maintain Individual Savings:

  • Open Separate Accounts: Each partner opens their own savings account.
  • Set Savings Goals: Determine specific goals, such as travel or personal projects.
  • Automate Savings: Choose to automate transfers to individual accounts regularly.

By following these steps, individuals can build personal financial security, promoting confidence in their decision-making.

Encouraging Personal Financial Growth

Support for each partner’s financial development is vital in a healthy relationship. Individuals can pursue education, investments, or side hustles that align with their interests and aspirations.

Ways to Encourage Growth:

  • Share Resources: Exchange books or tools that aid financial literacy.
  • Discuss Goals: Regularly talk about each other’s financial ambitions.
  • Celebrate Achievements: Acknowledge milestones and progress in personal finances.

By fostering an environment of support, both partners can thrive financially and individually. This practice not only strengthens the relationship but also enhances each person’s financial well-being.
 

What You Need To Understand About Jumbo Loans

When it comes to obtaining a loan, the process can be pretty complicated. If you are interested in getting a big loan, you’ll need to understand what that means and how it will affect your life. This article provides helpful information on what a jumbo loan actually is and how to go about getting one.

What is a Jumbo Loan?

A jumbo loan is a loan that has an aggregate loan amount of $1 million or more. These loans are popular with borrowers who need financing for large purchases, such as a home or a business expansion. There are a few things to keep in mind when applying for a jumbo loan:

  • The interest rate on jumbo loans can be higher than standard loans, and the terms may be longer. Also, jumbo loans typically require a down payment of at least 50%.
  • Jumbo loans are not available everywhere. Your bank may only offer jumbo loans to members of its lending syndicate.

How to Qualify for a Jumbo Loan

So that you can qualify for a jumbo loan, you should have a higher credit score than the traditional loan. Understand that lenders make use of your credit score to see if you are financially dependable. When you have a high score, then lenders will trust you more.

The lenders will usually go through the credit report and see if there are negative items like late payments, bankruptcy, foreclosures, missed payments, and others. So if you have experienced any of these in the past, then you have to wait until these items have been removed from your credit report. It may take 7 to 10 years from the date you reported for foreclosure or bankruptcy.

Also, the lenders will be checking your DTI ratio or the debt-to-income ratio. Lenders may think twice about approving you for a jumbo loan if the debt percentage is higher than your monthly income.

Benefits of a Jumbo Loan

If you are interested in getting a jumbo loan, then you should know the benefits that you can have from getting this kind of loan. Here are some of them:

  1. Flexibility. Jumbo loans offer more flexibility than smaller loans, allowing you to choose the terms that work best for you.
  2. Cost-effective borrowing. Jumbo loans are often cheaper than other types of loans, making them a good option if you need to borrow a large amount of money.
  3. More options. With a jumbo loan, you have more options for repayment and interest rates, giving you more control over your finances.
  4. Faster approval time. Jumbo loans usually take less time to approve than smaller loans, so you can get the money you need as quickly as possible.

If you’re looking for a big loan that offers all of the benefits listed above, a jumbo loan may be the right choice for you.

Drawbacks of a Jumbo Loan

From big-ticket items like cars and homes to everyday expenses, a jumbo loan can be the perfect solution for many people. But before you take out a loan that’s bigger than your average one, it’s essential to understand the potential drawbacks. For starters, jumbo loans come with higher interest rates and require larger down payments. That means you may have to borrow more money than you initially thought and could end up paying back more in total than if you had taken out a smaller loan.

Additionally, sometimes lenders will only approve loans if the borrower can prove they have a good credit score. If your credit is not stellar, a jumbo loan may not be an option at all. And finally, because jumbo loans are typically issued in amounts of $100,000 or more, they’re often difficult to get approved for without collateral, meaning you might need to sell something valuable if you want to borrow money from a lender.

Before taking out a jumbo loan, these factors are worth considering, but don’t let them scare you off entirely. If you find the right lender and have a solid financial plan in place, there’s no reason why a jumbo loan can’t be the perfect solution.

Are You Interested in Getting a Jumbo Loan?

If you have been contemplating that big purchase you want to pursue, then a jumbo loan can be the option to go for. Whatever that is, you must make sure you can repay the loan to avoid any issues.

Lenders often require applicants to undergo a pre-approval process before approving a jumbo loan. This means that your credit score will need to be sufficiently high and your income verified before you can even apply for this loan.

Several Ways a Canadian Family Will Protect Loved Ones Financially

As a Canadian family, financial protection for your loved ones is of utmost importance. While life insurance may be the first thing that comes to mind when considering financial security, there are other options that can help ensure your family’s financial future. From savings plans and investments to estate planning and disability coverage, there are multiple ways you can protect your family members from financial hardship in the event of an unforeseen circumstance.

When it comes to protecting against unexpected death, Policyme can provide Canadians with a life insurance quote. Then, when these quotes are turned into policies, it is not only peace of mind for families but a prudent way to financially plan. We have to think of the bigger picture so that we are effectively insuring everyone against the worst happening.

In this article, we will explore several options available for financial protection so that you can make the best decision to secure your family’s financial well-being.


The Protection of Life Insurance

Life insurance is a financial product that can provide monetary protection for your family members in the event of death or disability. The problem with not having it in place is that families can potentially be plunged into a state of financial disaster with bills to pay and the rising costs of living to afford.

Policies come in two main types: term and whole life. Term life provides financial aid to beneficiaries upon the policyholder’s death, while whole life builds cash value over time and can be used as a financial asset.

It depends on whether you want to link life insurance and savings together – you have that choice. It can be a very affordable and sensible option, however.


Savings Plans to Provide a Nest Egg

Savings plans are another way to protect your family’s financial future. These plans allow you to save money regularly and gain interest over time, helping to secure financial stability in the long term.

Retirement savings plans such as Registered Retirement Savings Plans (RRSPs) – for which you can use an rrsp calculator to estimate potential growth and tax benefits based on your contributions – and Tax-Free Saving Accounts (TFSAs) are popular options for Canadians and can be used to protect financial assets in times of financial hardship.

Many will doubt whether saving is the best option when money is needed for day-to-day living but will wish that they had kept some money separate further down the line. In retirement, income dries up to an extent, albeit what we receive from a pension plan, so savings become all the more important for us to continue to live comfortably.


Estate Planning

Estate planning is another key factor when it comes to financial protection. A good estate plan can help ensure that your family’s financial future is secure, even after you are no longer able to provide financial support.

Such plans should include financial documents such as powers of attorney and health care directives, as well as financial instruments like wills and trusts.


Disability Coverage

Finally, disability coverage can provide financial protection for you and your family in the event of illness or injury that prevents you from working.

Disability insurance offers financial compensation to policyholders who are unable to work due to illness or injury, helping to keep financial hardship at bay during difficult times.


Conclusion

When it comes to protecting our family financially, there are many options available that can help you and your loved ones stay secure in the future. Life insurance, savings plans, estate planning, and disability coverage are just some of the ways you can ensure you have covered your family financially in the case of an unpredictable and unforeseen circumstance.

By considering all these options and taking the necessary steps to secure financial protection as much as possible for your loved ones, you can help ensure that your family can continue to fund their established lifestyle.

Several Ways a Canadian Family Will Protect Loved Ones Financially

As a Canadian family, financial protection for your loved ones is of utmost importance. While life insurance may be the first thing that comes to mind when considering financial security, there are other options that can help ensure your family’s financial future. From savings plans and investments to estate planning and disability coverage, there are multiple ways you can protect your family members from financial hardship in the event of an unforeseen circumstance.

When it comes to protecting against unexpected death, Policyme can provide Canadians with a life insurance quote. Then, when these quotes are turned into policies, it is not only peace of mind for families but a prudent way to financially plan. We have to think of the bigger picture so that we are effectively insuring everyone against the worst happening.

In this article, we will explore several options available for financial protection so that you can make the best decision to secure your family’s financial well-being.

The Protection of Life Insurance

Life insurance is a financial product that can provide monetary protection for your family members in the event of death or disability. The problem with not having it in place is that families can potentially be plunged into a state of financial disaster with bills to pay and the rising costs of living to afford.

Policies come in two main types: term and whole life. Term life provides financial aid to beneficiaries upon the policyholder’s death, while whole life builds cash value over time and can be used as a financial asset.

It depends on whether you want to link life insurance and savings together – you have that choice. It can be a very affordable and sensible option, however.

Savings Plans to Provide a Nest Egg

Savings plans are another way to protect your family’s financial future. These plans allow you to save money regularly and gain interest over time, helping to secure financial stability in the long term.

Retirement savings plans such as Registered Retirement Savings Plans (RRSPs) and Tax-Free Saving Accounts (TFSAs) are popular options for Canadians and can be used to protect financial assets in times of financial hardship.

Many will doubt whether saving is the best option when money is needed for day-to-day living but will wish that they had kept some money separate further down the line. In retirement, income dries up to an extent, albeit what we receive from a pension plan, so savings become all the more important for us to continue to live comfortably, whether that’s in our own home, or somewhere like this chelseaseniorliving.com/locations/new-jersey/manalapan/ senior living facility, where there is support from caregiving professionals available 24/7.

Estate Planning

Estate planning is another key factor when it comes to financial protection because it can help ensure that your family’s financial future is secure, even after you are no longer able to provide financial support. It is also a highly effective way of passing down certain assets, properties or funds to specific individuals inside or outside a family.

But a comprehensive estate plan should include at least the legal documents stating alberta power of attorney (if that’s where you live), a testament or will, beneficiary designations, a letter of intent, and an advance care directive. Providing a compilation of individual documents solidifies the case, ruling out the scope of any issues that might come up when executing the estate plan.

Disability Coverage

Finally, disability coverage can provide financial protection for you and your family in the event of illness or injury that prevents you from working.

Disability insurance offers financial compensation to policyholders who are unable to work due to illness or injury, helping to keep financial hardship at bay during difficult times.

Conclusion

When it comes to protecting our family financially, there are many options available that can help you and your loved ones stay secure in the future. Life insurance, savings plans, estate planning, and disability coverage are just some of the ways you can ensure you have covered your family financially in the case of an unpredictable and unforeseen circumstance.

By considering all these options and taking the necessary steps to secure financial protection as much as possible for your loved ones, you can help ensure that your family can continue to fund their established lifestyle.

Should I Increase My Credit Limit?

Everyone is in a hurry these days. Whether it’s a rush to get to work early to make it on time or a rush to get that promotion that you need to nail, there’s always that key moment when you realize you’re behind on your bills. It’s that moment that provides the deadline you need to make your payments on time. Is this the sign that you need to increase your credit limit? We don’t know about you, but we think it is time for your to do that.

Increased Credit Limit comes with Great Benefits

One of the most common questions asked on the Internet today is, “Should I increase my credit limit?” The answer to this question is one of the most difficult to give because it depends on so many factors. But, increasing it also gives you a lot of benefits.

Here are the following benefits that you’ll get when you increase your credit limit:

  • It is easier and cheaper to apply for home loans from certified and licensed lenders (similar to a net branching mortgage). When you apply for a credit card, car loan, or mortgage, you can request an increase in your credit limit. This is because credit agencies are obliged by law to give you more credit if you want to borrow more money. This can be a benefit of increasing your limit when you already have a good credit score. In addition to this, a positive credit score allows you to borrow money against any assets that you own, no matter what type of asset they are. If you have a life insurance policy, then you are likely to get a loan against your life insurance as long as you maintain a good credit score (if you are interested, see the relation between loans and life insurance here).
  • It lowers the borrower’s credit utilization. Have you ever wanted to increase your credit limit but were concerned about the changes in your utilization? Well, many people have done so, but if you look at past increases in the limit, it’s clear that a lot of people who have increased their credit limit have experienced a decrease in their credit utilization.
  • You earn more rewards. Credit cards are a great way to make your purchases more affordable, and some of them, known as rewards credit cards, can help you earn rewards points that can be redeemed to get free stuff. However, it is important to know that if you do not pay your balance in full every month, you can get your credit limit increased, once it has been increased, you can continue to earn rewards points while paying the additional credit card charges.
  • It is a great help during unforeseen emergencies. One of the advantages of increasing credit limits is that you gain access to a credit card safety net in case you have a genuine emergency that you can’t pay for with cash. The easiest way to do this is to set up a credit limit that you can’t afford to spend more than in a month because that way, you can always use your credit card to pay for your monthly bills. Even if you have an emergency, you’ll have enough cash left to pay for your expenses, which is often more than enough to cover expenses.
  • It prevents you from getting credit score dings. If you want to increase your credit line but are afraid of the repercussions of an increased credit limit, you may want to know the important benefits of increasing your limit. These include not having a credit score ding on your report, protecting your images, and avoiding the risk of having your score drop. A low credit score means that you’re less likely to be approved for a mortgage. However, a high score means that you’re more likely to be approved for it. Say that you want to apply for a mortgage with the Moreira Team- acclaimed as one of the top-rated mortgage companies in ga. Now, if you have a good credit score, chances are that you would secure the finances. Wondering why? A credit score is actually a prediction of how likely you are to pay a loan back on time based on information from your credit reports. So, if the reports show that are punctual while returning money, then nobody would question your credibility. That said, while you can always talk to adverse credit mortgage brokers to find other ways of obtaining the funds you need, it might still be a good idea to ensure that your score stays on the higher side.
  • It enables you to make large purchases. Purchasing large items such as a house, a car, or even a laptop can be expensive. Credit cards have such a high limit on them because it allows you to make a large purchase without having to pay interest. If you’re not cautious about reaching your limit, you can end up paying for the next 10 years of interest as well as the money you spent on the item.

You’ve probably heard that taking out a larger credit card limit can help you build your credit and make it easier to qualify for loans in the future. However, there are many factors that determine whether the limit increase is the right move for you. In fact, it’s important to understand some of the negative consequences of a larger credit card limit before you go ahead and make the change.

Savings Account: Which Type Is the Best

Saving is hard, but saving money is even harder. Why? Because saving takes time and discipline, and let’s face it, none of us has that to spare. So, what’s a cash-strapped person saving for their first home, or to be able to move to somewhere like this senior housing in Lincoln community and enjoy their retirement, to do? The most obvious answer is to open a crudely named savings account. But which type is best?

What Is a Savings Account?

A savings account is a financial account that allows you to save money in small amounts, typically with a fixed interest rate. It is typically used for short-term savings goals such as a vacation, home improvements, or an emergency fund. These accounts can be either insured or uninsured.

Here Are the Six (6) Types of Savings Accounts

  • Traditional or Regular Savings Account – A traditional or regular savings account is a savings account that earns interest, usually from banks and other financial institutions. These savings accounts follow FDIC bank deposit insurance rules and typically offer higher interest rates on larger balances. Traditional savings accounts typically offer higher interest rates than money market accounts designed for people looking to keep a small amount of money available for emergencies.
  1. High-Yield Savings Account – A High-Yield Savings Account (HSA) is a tax-exempt savings account that will allow you to put aside funds to pay for eligible medical expenses. To qualify for an HSA, you must have a high-deductible health plan. This generally means health coverage with a deductible that is at least twice as much as your annual household income. The money deposited into an HSA is considered non-taxable.
  2. Money Market Accounts – A money market account (MMA) is a savings account that’s different from a regular savings account. You can’t access your money often (typically more than 6-12 times per year). However, an MMA often has higher interest rates than regular savings accounts, so it’s generally a good place to park the money you want to save, but you don’t want or need immediate access to. With MMAs, your money is FDIC insured, just like with a regular savings account, so your money is in good hands. If you are planning a trip or doing something adventurous that you have always wanted to do, it could be a good way to save money for that. For example, by saving money in this type of account, you could sponsor a trip to a sport such as flying a spitfire through https://spitfires.com/, skydiving, or even a world tour.
  3. CD Account – CD Account is your full-service credit union online and mobile app that provides convenience and control of your accounts. With a CD Account, you can manage your accounts anywhere, anytime, 24/7. An easy-to-find phone number and email address are available 24/7 for any questions you may have. CD Account is free on all accounts, including checking accounts, savings accounts, money market accounts, and certificates. There are no minimum balance requirements, no monthly fees, no per-check fees, and no per debit card fees.
  4. Cash Management Account – Cash management accounts, or CMAs, are checking accounts designed for business owners who deposit larger amounts more frequently. They are commonly touted as an effective means for managing cash flow, tracking spending, and lowering costs. CMAs even offer other potential benefits, such as higher interest, reimbursements for expenses, and preferential rates on loans.
  5. Specialty Savings Account – A specialty savings account, also called a 529 account, is a type of college savings plan that’s designated by a state. These plans are different from regular 529 accounts, which let you save for higher education because you’re able to invest money specifically in specialized programs, such as computer science, architecture, and music. A specialty savings account requires a lot of planning, so you’re confident you’ll have enough money to pay for college.

Why Would You Put Money in a Savings Account?

Here are some reasons why it can make to put money in a savings account.

Saving money can be challenging, but putting money aside is easier when you understand the benefits you’ll receive from your savings account.

  1. Build an emergency savings fund
  2. Reduce your debt
  3. Save for a down payment on a house or car
  4. Make retirement dreams a reality
  5. Make a down payment on another home

Savings accounts are one of the best ways to sock away money. With interest rates occasionally hovering in the zero and low-teens, savings accounts are earning less than they ever have since the recession. However, there’s good news for savers. Some banks are now offering interest rates on savings accounts that rival or even beat pre-recession rates. With such conveniences, your savings may increase with time, which may further help you fulfill your needs after retirement. In case you want to shift to an adult living society (if interested, check out this community) with your retired friends, you can use these savings to purchase or rent a home. Nowadays, hospital bills and medicines generally make a person short on cash, these savings can help you in bailing out of this situation too.

Considering which type of savings account is best for you based on our simple criteria below if you’re looking to save. Along with saving accounts, you may need to invest your money in stocks, bonds, and mutual funds. But you may have to be very cautious while investing in a specific plan. A brief consultation with a financial advisor like Lincoln Frost can help you create numerous passive income sources.

With the implementation of such ideas, you can diversify your income sources along with your job or business. You could further invest your earnings in real estate and precious jewelry (like gold, platinum, and silver). At last, a quote related to the importance of money management-“Finance is not merely about making money. It’s about achieving our deep goals and protecting the fruits of our labor. It’s about stewardship and, therefore, about achieving the good society.” – Robert J. Shiller.